Car Insurance for Maruti Suzuki Vehicles: Coverage, Benefits, And Add-Ons
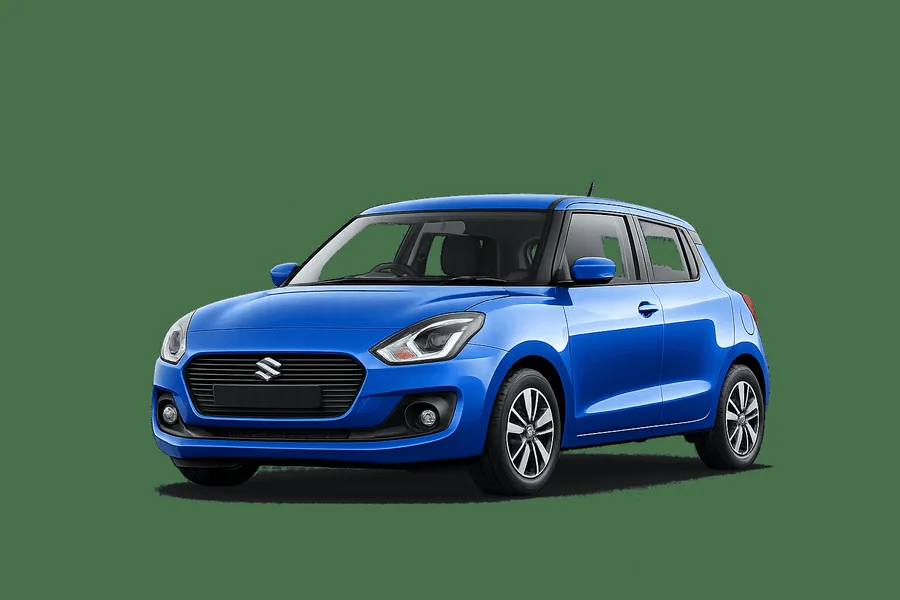
If you own a Maruti Suzuki car, the insurance basics are the same as they are for other private vehicles. What can differ are the details of the vehicle and the policy, including its age, model, IDV, usage, and available add-ons. So, if you are looking up car insurance online, it helps to know which features of the policy deserve your attention.
What Does a Car Insurance Policy Cover?
A motor insurance policy can include third-party liability cover and own-damage cover. Third-party liability relates to your legal liability for injury, death, or property damage caused to a third party. Own-damage cover relates to loss of or damage to your insured car, subject to the terms of the policy.
The exact scope of own-damage cover depends on the policy. The same applies to exclusions, deductibles, limits, and other conditions. The fact that the car is a Maruti Suzuki does not, by itself, determine the extent of the insurance cover.
Which Add-Ons Can You Consider for Your Maruti Suzuki Car?
Add-ons are additional covers that address specific areas of protection. Depending on the policy, these can include zero depreciation, engine protection, roadside assistance, or consumables cover.
For example, zero depreciation cover relates to the treatment of depreciation on eligible parts. A consumables add-on can address specified items used during repairs, while roadside assistance is for certain breakdown or roadside situations. Each add-on has its own scope, so they should not be treated as interchangeable.
Does Your Maruti Suzuki’s Age Affect the Add-Ons Available?
It can. Some add-ons may have vehicle-age or eligibility conditions, and their availability can vary between insurers and policies.
This is particularly relevant when you renew an older Maruti Suzuki. An add-on that was available when the car was new may not necessarily remain available on the same terms later. The applicable policy wording can tell you which options are available for the vehicle at that point.
Why Does IDV Matter?
The Insured Declared Value, or IDV, is the sum insured for the insured vehicle under the own-damage section of the policy. It is an important figure because it represents the value assigned to the vehicle for the policy period.
IDV is not the original purchase price of your Maruti Suzuki car. It is determined based on the applicable valuation method and can change as the vehicle ages.
What Should You Check Before Renewing Your Policy?
A renewal is a useful point to look at more than just the premium. Check whether the following still reflect your current vehicle and requirements:
- IDV: Check the value assigned to your car for the policy period.
- No Claim Bonus: Check the NCB applicable to your own-damage premium, subject to the relevant rules.
- Add-ons: See which additional covers are included and the conditions attached to them.
- Deductibles: Note the amounts applicable under the policy.
- Policy details: Check that your car’s registration, model, and other vehicle information are accurate.
What Should You Look for in Maruti Insurance Online?
Searching for Maruti insurance online can bring up different policy options for the same vehicle. Rather than focusing only on the premium, look at the type of cover, IDV, deductibles, add-ons, NCB, and the conditions attached to each option.
The model and age of your Maruti Suzuki can also matter when you look at available add-ons and eligibility. The policy document provides the details that apply to the cover you are considering.
Conclusion
A Maruti Suzuki does not need a separate insurance framework simply because of its brand. What matters is how the policy fits the particular vehicle and the cover it requires. Looking beyond the brand name and at the actual policy details gives you a clearer view of what the insurance offers.